


BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
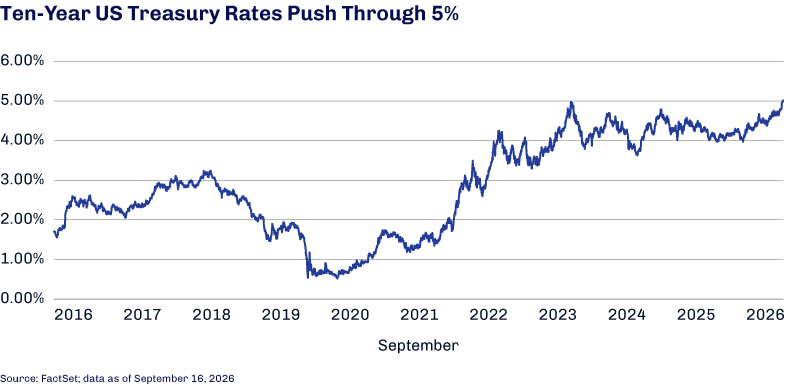
Fed Chair Warsh followed through on his anti-inflation rhetoric on Wednesday, as the Federal Open Market Committee voted unanimously to increase the federal funds target rate by 25 basis points to a range of 3.75–4.00%. The dot plot of policymaker forecasts, meanwhile, suggests one more hike is likely before year end. After easing slightly throughout the day, the 10-year Treasury yield moved higher following the announcement to finish above 5%; the two-year note followed a similar trajectory. The dollar strengthened, and equity markets fell.1
The hike reaffirms our long-held view that we are in a higher-for-longer interest rate environment and temporarily restores our faith in the Fed as a staunch inflation fighter. Given the political costs that may accompany the move, however, it remains to be seen whether we have entered a prolonged hiking cycle or if this hike represented a one-off that will be followed by more “data-dependent” decisions moving forward. This uncertainty combined with Warsh’s resistance to forward guidance suggest to us that the bond market is likely to remain volatile.
As we have said before, raising front-end interest rates is not a magic bullet for combating inflation. While excess demand was a key driver of the post-Covid spike in inflation and responded well to higher interest rates, we believe today’s inflation is attributable primarily to supply disruptions. This is perhaps most evident in the energy market, where prices are likely to remain elevated unless the Iran war comes to a successful conclusion in the coming months. Consumers facing higher direct energy prices are also being hit by the higher costs associated with the trucking of everyday goods; costlier imported fertilizer also may push food prices higher, though with a lag.
Meanwhile, the Fed has no obvious mechanism to address the major issues plaguing the US economy; the remedy resides within the executive and legislative branches of the government. While an end to the Iran war likely will help reduce energy-related inflation in the near term, the long-term impact of the ever-increasing deficit will persist without concerted action. The markets need proper remedies for a long-term cure, in our view, not a short-term pain killer.
An insurer constantly makes capital-allocation decisions: which risks to underwrite and at what price, how to invest premiums, and whether surplus should support growth, acquisitions or shareholder returns. For decades, however, Japanese insurers held substantial shares in corporate clients partly to reinforce commercial relationships, not solely for investment returns.
These cross-shareholdings tied up capital, increased equity-market exposure, and made it harder to judge whether insurance was appropriately priced. Governance reform, regulatory scrutiny, and industry misconduct are now accelerating the unwinding of this system.
The unwind therefore tests insurers twice: whether they can retain business and price risk appropriately without reciprocal relationships, and whether they can deploy the capital released at attractive returns. The first test should reveal the strength of the underlying franchise as insurers compete increasingly on service and underwriting discipline.
The second test is what management does with the proceeds. Repurchases below intrinsic value can enhance value per share. Reinvestment can strengthen a competitively advantaged domestic franchise or an overseas business whose underwriting, capital, data, and reinsurance capabilities reinforce one another. Acquisitions made principally to sustain growth may result in shareholders owning a loose collection of businesses.
We think it’s important to distinguish strong capital allocators from companies merely selling holdings.
Insurers must retain ample resources for catastrophes and unexpected losses. Reported profit can be misleading because gains on equity sales can be large but are non-recurring and do not reflect underlying profitability. We instead focus on balance-sheet, normalized underwriting earnings, reserve discipline, and the prospective return on each yen retained.
For long-term investors, this is a multi-year effort to turn underused capital into stronger businesses and grow intrinsic value per share, not primarily a trade on Japan’s economic growth, interest rates, or the yen. The opportunity may be substantial, but it is not uniform. We think bottom-up research can identify management teams that can potentially convert finite capital release into durable compounding.