BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
October brought a shift in securitized markets as Treasury yields declined and credit spreads widened amid a flight to quality. Despite changing market conditions, issuance remained strong, while consumer credit fundamentals continued to show resilience.
Consumer Credit Holds Steady1,2
Third-quarter earnings from major consumer lenders painted a generally positive picture of household credit. Auto lenders and credit card issuers reported stable credit performance and resilient spending, particularly among higher-quality borrowers. However, signs of more selective spending among lower-quality consumers reinforced the growing divide across borrower segments.
This divergence was also a central theme at the Asset-Backed Securities (ABS) East conference, where discussions focused on underwriting discipline, sponsor quality and downside protection. Emerging sectors, including data center ABS, raised additional questions around power availability, technological obsolescence and long-term demand.
Issuance Remains Robust1
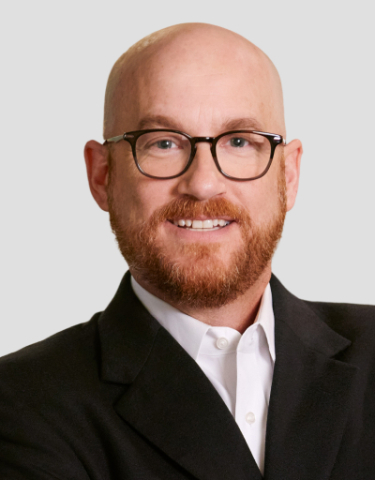
ABS issuance reached $30.8 billion in October, bringing year-to-date volume to $314.8 billion, ahead of comparable periods in 2024 and 2025. Auto ABS accounted for more than half of October's issuance, while data center and fiber transactions represented nearly 15%.
Non-agency residential mortgage-backed securities (RMBS) issuance also continued to accelerate, reaching $203 billion year to date, up 19% from 2025, driven largely by non-qualified mortgages.
Commercial Real Estate Pressures Persist3,4
Commercial mortgage-backed securities (CMBS) delinquencies remained elevated, with the overall delinquency rate reaching 7.87% in October. Office properties continued to face pressure, while non-agency CMBS issuance climbed to $149 billion year to date, 16% ahead of 2025.
As securitized markets evolve, resilient issuance and uneven credit trends underscore the importance of disciplined underwriting and security selection.
Staying Selective as Deal Volumes Decline

Senior Managing Director and Chief Investment Officer of Direct Lending, Napier Park Global Capital
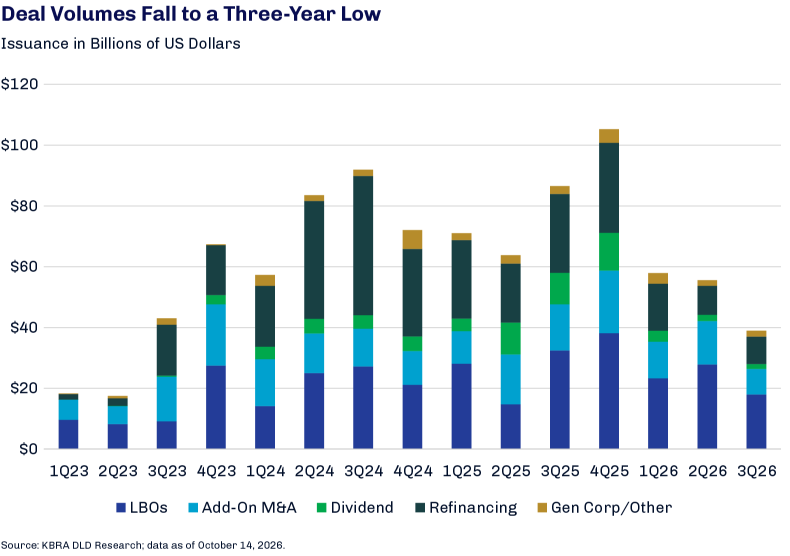
Direct lending deal volume slowed to a three-year low during the third quarter, as leveraged buyout (LBO) and add-on merger and acquisition (M&A) activity were both weak; at $152 billion year-to-date, volume is running 31% short of 2025’s pace.1
Additionally, some of the margin expansion within the core and upper middle markets from the first half of 2026 made its way to the lower middle market, where spreads widened by 11 basis points in the quarter. While core and upper middle market spread expansion was likely driven by software exposure—which continued to see the most default activity—we believe the widening of lower middle market spreads reflected a general market correction of the underpriced illiquidity premium for smaller borrowers. Spread per turn of leverage, in contrast, narrowed to its lowest level since August 2025.2
Covenant-lite structures accounted for 17% of direct lending deals through third quarter 2026—up from 14% in 2025—concentrated in the upper middle and large cap markets; cov-lite structures represented less than 3% of deal flow in core and lower middle market loans. Lower middle market default rates over the past 12 months, at 1.8% by dollar amount and 1.5% by deal count, declined since last quarter and remain below 2025 levels.3
Despite the recent rate increase, we anticipate that deal flow could continue to improve through year end, allowing for deployment in an attractive yield environment. We remain focused on selectivity as we evaluate opportunities across industries and subsectors. However, we are skeptical of market lending trends—such as data centers—as we continue to target essential service businesses, which we believe are more insulated from artificial intelligence (AI). We have also pulled back slightly on healthcare given longer hold periods within certain subsectors, and we continue to be cautious on software.