BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
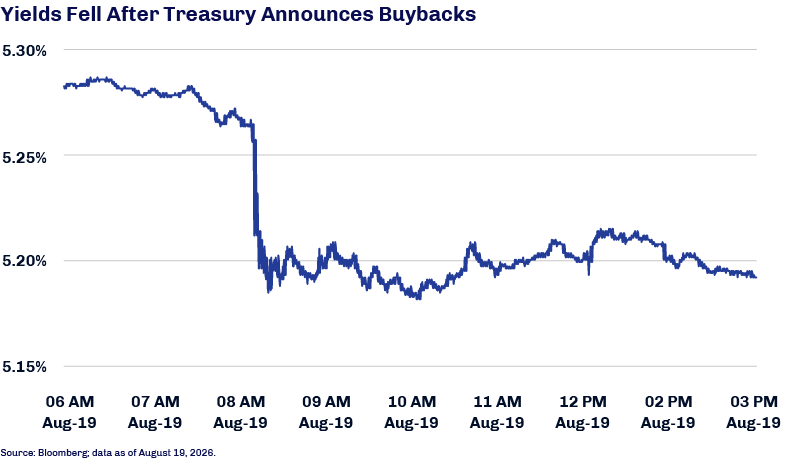
US Treasury Secretary Scott Bessent announced plans to at least double buyback support for longer-dated government bonds with the goal of reducing longer-term yields. This buyback announcement had an immediate and measurable impact on yields—the 30-year Treasury yield fell by as much as 10 basis points after recently reaching its highest level since 2007.1 But we are skeptical of the sustainability of the relief.
We estimate that the implied size of these buybacks would total $28 billion, which is relatively small compared to the $4 trillion balance of outstanding bonds at these tenors.2 Additionally, to the extent that this buyback does ease longer term rates, it does so at a time when financial conditions are already quite easy and inflation pressures persist.
Perhaps more troubling, the Treasury will need to issue more shorter-dated debt to fund these buybacks, implying more interest-rate risk for the Treasury down the road when maturing obligations must be refinanced at higher prevailing rates. This rollover risk is particularly problematic in light of today’s fiscal situation with a large primary deficit and high federal debt.
While government intervention in other sovereign bond markets—typically in emerging economies—have sometimes been effective during periods of stress and dislocation, a small intervention by US Treasury seems inadequate to offset the slow grind-up in Treasury yields due to higher expected short rates and higher term premiums on longer bonds. Moreover, we think efforts to contain the cost of debt through financial repression rather than adopting fiscal discipline to reduce deficits will eventually take its toll and be felt in other markets, as gold strengthened and US dollar weakened in tandem with this announcement.3
Record issuance can look like a vote of confidence, but in securitized credit it is better viewed as an expanding opportunity set.
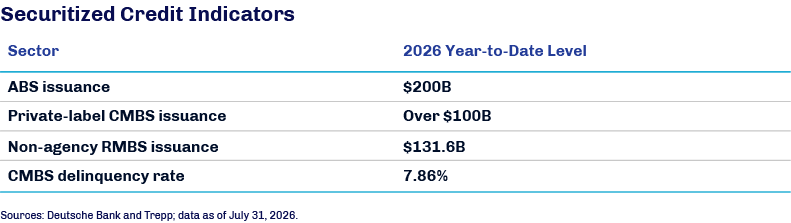
In 2026, issuance has accelerated across asset-backed securities (ABS), commercial mortgage-backed securities (CMBS) and residential mortgage-backed securities (RMBS). ABS issuance reached $200 billion by early July, ahead of the record-setting 2024 pace. Private-label CMBS issuance surpassed $100 billion by the end of July, while non-agency RMBS issuance totaled $131.6 billion year to date.1
But what lies beneath the strong issuance? And what does it tell us about credit performance?
CMBS delinquencies rose to 7.86% in July from 7.23% a year earlier. Office properties remained a notable pressure point, with delinquencies reaching 11.91%, while multifamily delinquencies rose to 7.69%. Industrials were the lone bright spot, with delinquencies declining to 1.13%.2
Consumer-related credit trends appeared more constructive. Major card issuers reported healthy spending growth, while some lenders improved their credit-loss outlooks. Data-center securitization also remained active, with $17 billion of issuance year to date.3
Non-agency RMBS issuance reached $131.6 billion year to date, with non-qualified mortgage securities accounting for nearly half of July volume. Second-lien and home equity line of credit issuance also reached $24 billion year to date—the strongest pace since the financial crisis.4
For investors, increased issuance may create more opportunity, but disciplined underwriting, structural analysis and careful security selection remain crucial.