


BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
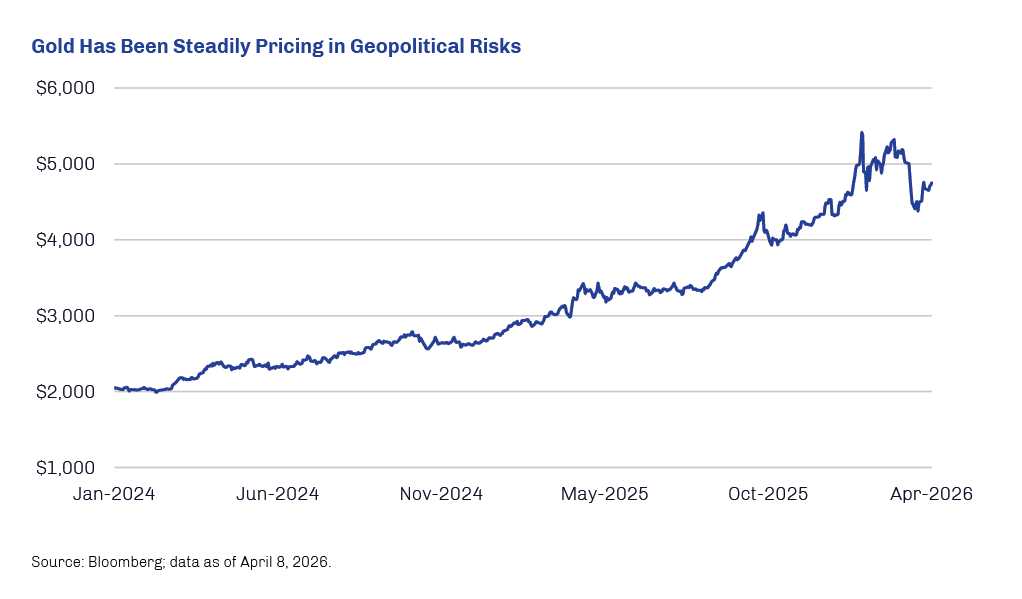
We often note how gold can sometimes serve as a proverbial canary in a coal mine, sussing out potential dangers before they are perceived by the financial markets more broadly.
This prognostic ability may help explain the massive advance in gold over the past two years through periods in which traditional drivers of the gold price—such as the direction of real and nominal interest rates, US dollar strength and central bank policy bias—were not always supportive of a rally. Essentially, it appears that gold had been steadily pricing in a large-scale geopolitical event, which ultimately came to fruition when war broke out between the US/Israel and Iran on February 28. In fact, with the drumbeats of war growing louder, gold surged 14% in January, preceding advances in integrated oil majors and spot oil prices. 1
Importantly, war changed the calculus of gold ownership, and record-high prices needed to adjust to its monetary and financial implications, including higher inflation and a more hawkish Federal Reserve. While some may view the subsequent volatility in the gold price as a disappointment given its reputation as a store of value during challenging times, those with a strategic allocation to the metal over the past couple of years have benefited handsomely.2
While markets, including gold, let out a sigh of relief with the ceasefire agreement on April 7, risks remain abundant. The Iran conflict is far from resolved, and the fighting between Ukraine and Russia has entered its fourth year with no end in sight. Meanwhile, economies worldwide face troubling debt dynamics and the potential for continued currency debasement. In other words, the long-term fundamentals for gold—and the case for strategic portfolio exposure—remain strong even as short-term trends may occasionally batter the price.3
Concerns about the disruptive impact of artificial intelligence on the technology landscape have seeped into the credit markets. The resulting barrage of headlines in the financial media has some investors questioning the quality and stability of private credit portfolios given the large exposure many traditional private lenders have to the software industry borrowers.
Private credit encompasses a wide array of assets beyond senior-secured corporate loans, and the characteristics of these disparate assets can have a significant impact on the management of fund structures that offer periodic liquidity, such as interval funds.
Take, for example, certain segments of the residential real estate lending market, such as residential transitional loans. Residential transitional loans generally have maturities of about one year, far shorter than the usual five-year maturity of a corporate loan. As a result, residential transitional loans typically return principal faster than corporate loans, creating higher levels of recurring organic liquidity that can support investor redemptions. While corporate loan portfolios may still meet repurchase requests, they are generally more dependent on active liquidity management because principal stays tied up longer.
Certain segments of the residential real estate lending market feature loans with far shorter maturities than corporate loans.
We believe potential liquidity effects may snowball over time, which include:
- The potential for faster paydowns on outstanding loans can help the loan manager to 1) rebuild liquidity between windows rather than simply depleting it over time, and 2) opportunistically redeploy assets in times of stress for the broader markets.
- With active liquidity management not an issue, the manager can allocate a greater proportion of private assets than strategies with longer loan maturities held in semi-liquid structures.
- Even if a traditional private loan portfolio is able to meet a quarter’s redemption demand without forced asset sales, ongoing elevated demand may slowly pressure the manager to more actively manage liquidity.
- The high level of organic principal collection enables the residential real estate loan manager to potentially allow a higher level of redemptions without selling assets at unattractive prices.