BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
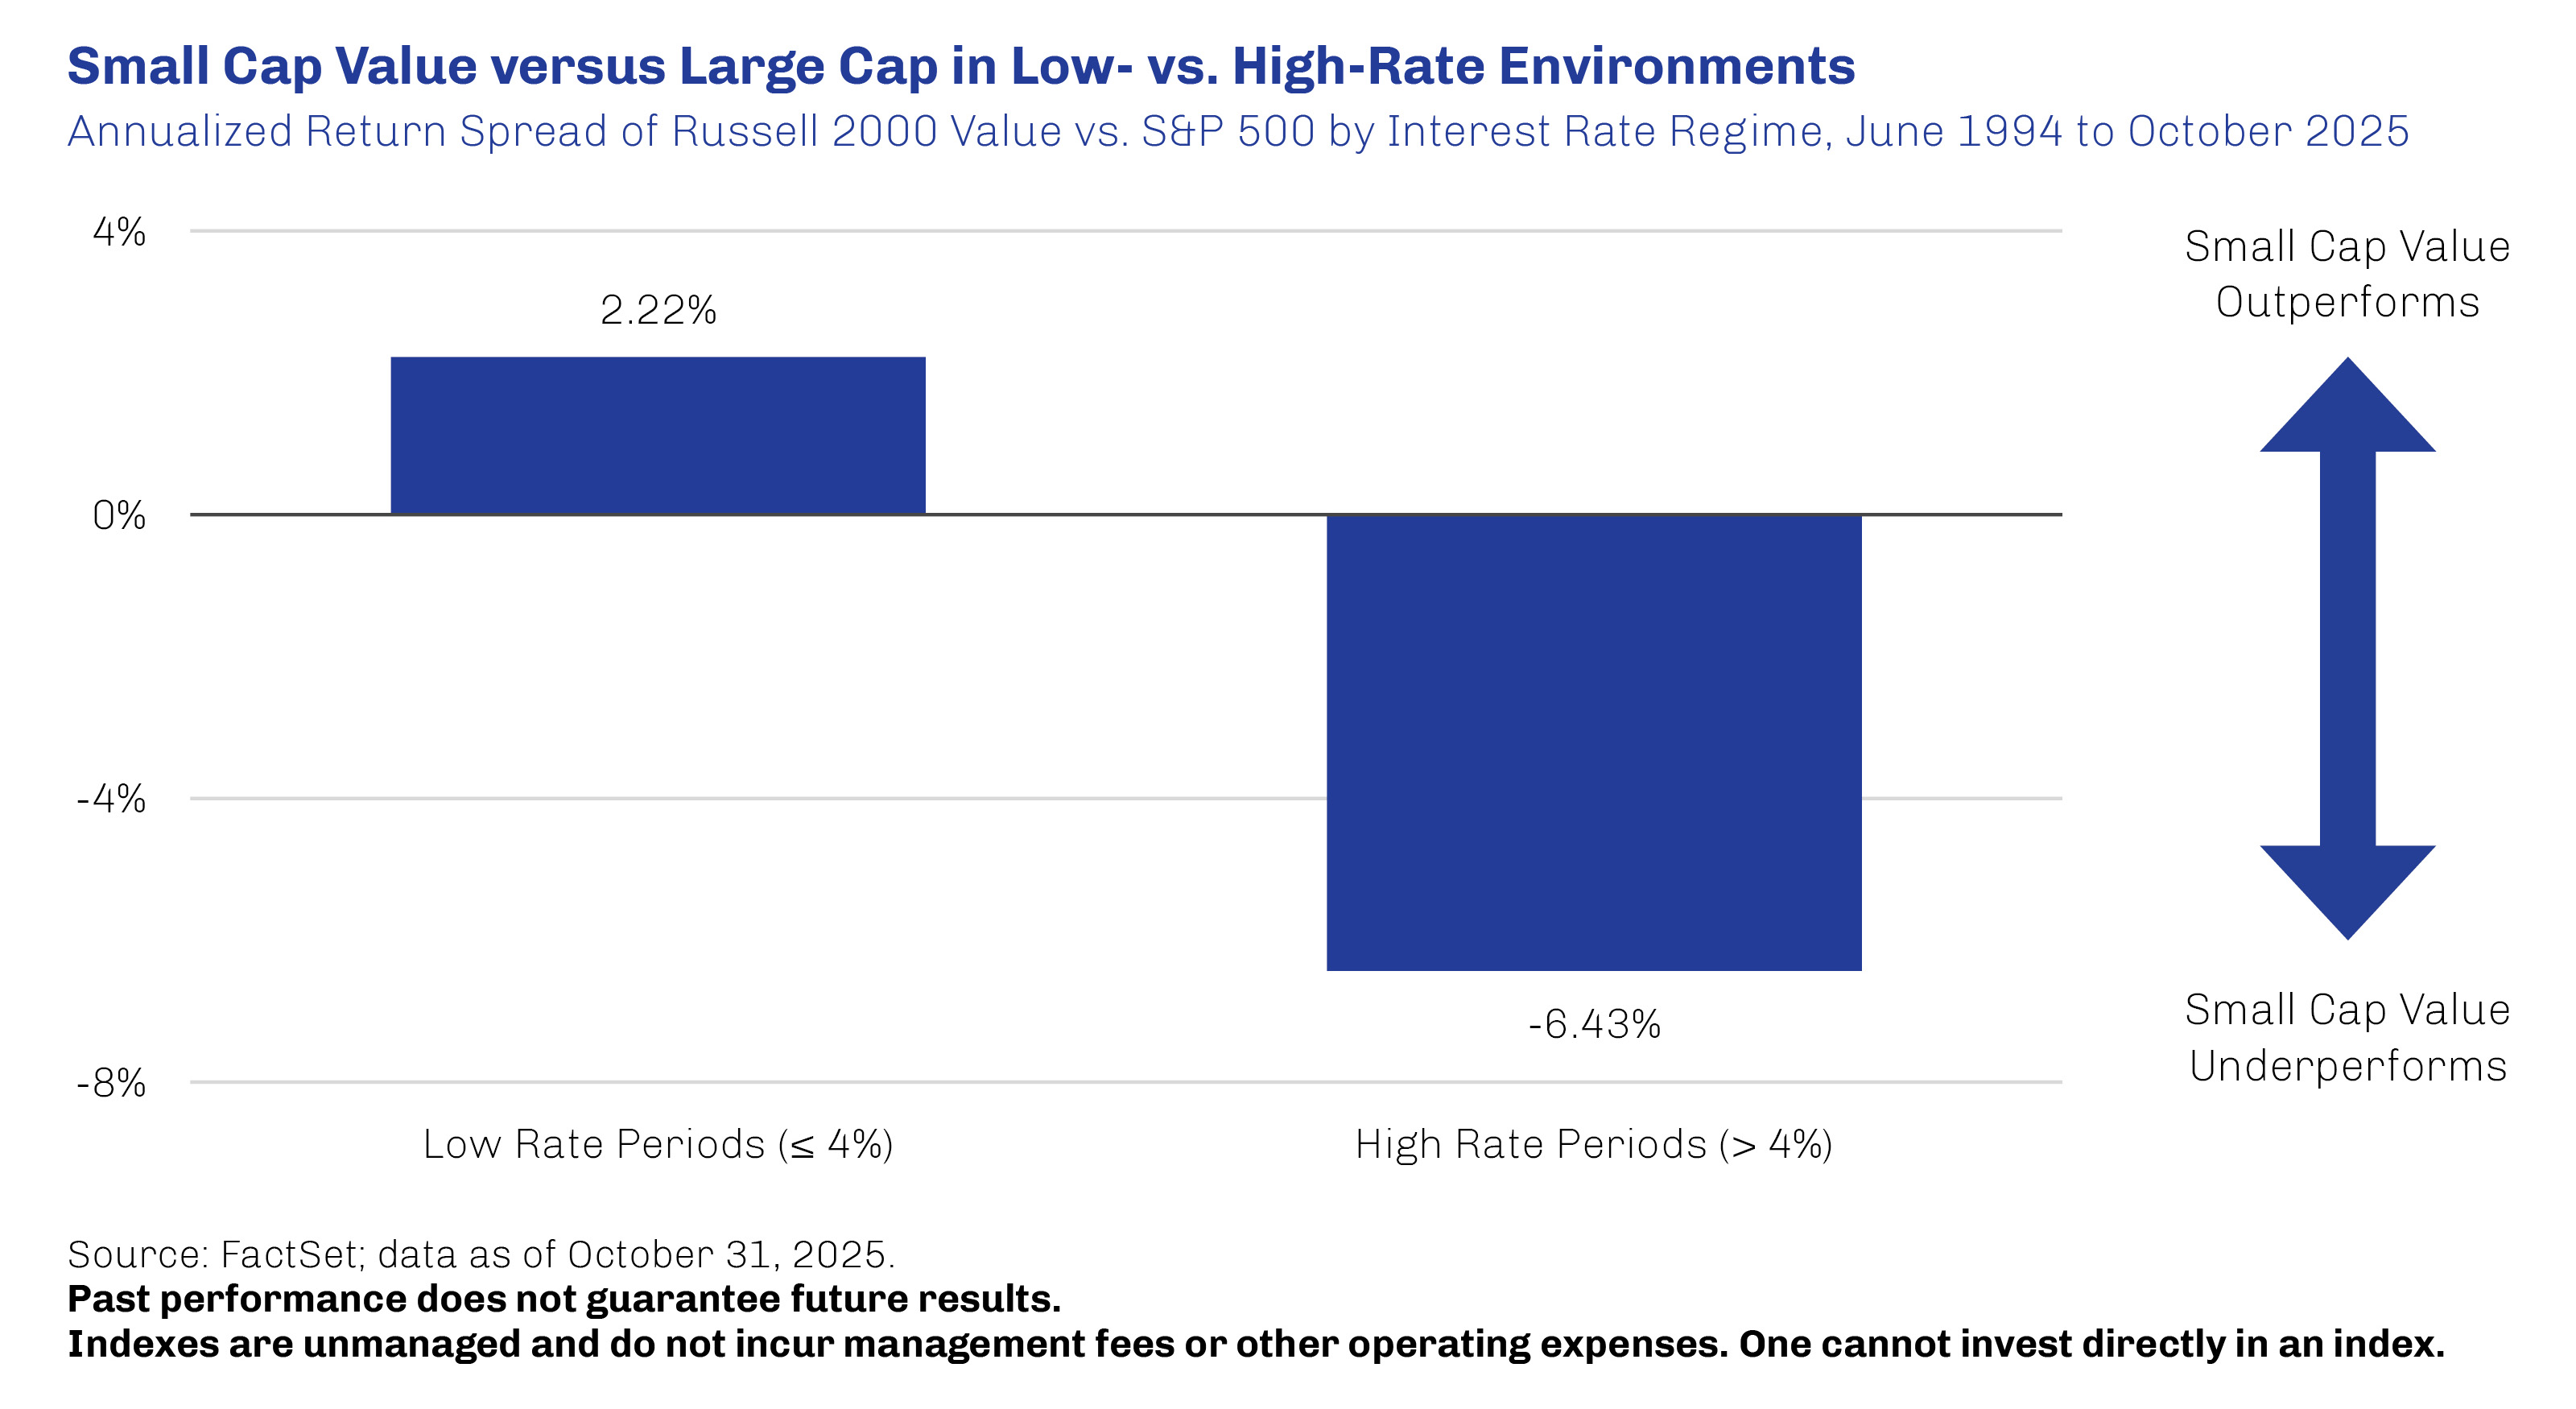
Over the past several years, small cap equities have dealt with a policy backdrop defined by aggressive rate hikes and tightening financial conditions. Historically, small cap companies—which are more reliant on floating-rate or shorter-term debt and domestically oriented—have tended to lag in high-rate environments but outperform once borrowing costs decline.1
Historical data show that when interest rates are at or below 4%, small cap value stocks outperform large caps by an average of just over 2% annually. In contrast, when rates rise above 4%, we see small cap lag by over 6% annually.2
This dynamic underscores how rate regimes can shape performance across the equity landscape. Small cap companies, which tend to be more leveraged and rely more heavily on short-term borrowing, often face greater pressure when financing costs rise. Conversely, when rates stabilize or begin to decline, improved access to capital and stronger operating leverage can fuel meaningful recovery.
At the end of the third quarter, valuations across the small-cap universe appear compelling relative to historical averages. The Russell 2000 Value Index traded well below historical average with a forward price-to-earnings (P/E) ratio of roughly 14x, compared to roughly 25x for the S&P 500 Index.3 These lower valuations may offer a wider margin of safety should monetary policy continue to ease further.4
As the Federal Reserve has begun to cut rates, with the potential for further cuts, easing credit conditions and stronger domestic demand could benefit small caps. The combination of discounted valuations and historical interest rate sensitivity highlights the importance of maintaining selective exposure to small cap equities within a diversified portfolio.
The “Korea Discount” Gets a Value-Up Turnaround
Head of Global Value Team and Portfolio Manager
While the year-to-date outperformance of non-US equities relative to US names may be attributable to a natural ebb and flow of markets around the long-term mean, the rebound in certain markets may also be a function of secular forces that have awakened animal spirits. One such instance is corporate governance and tax reform in Korea.
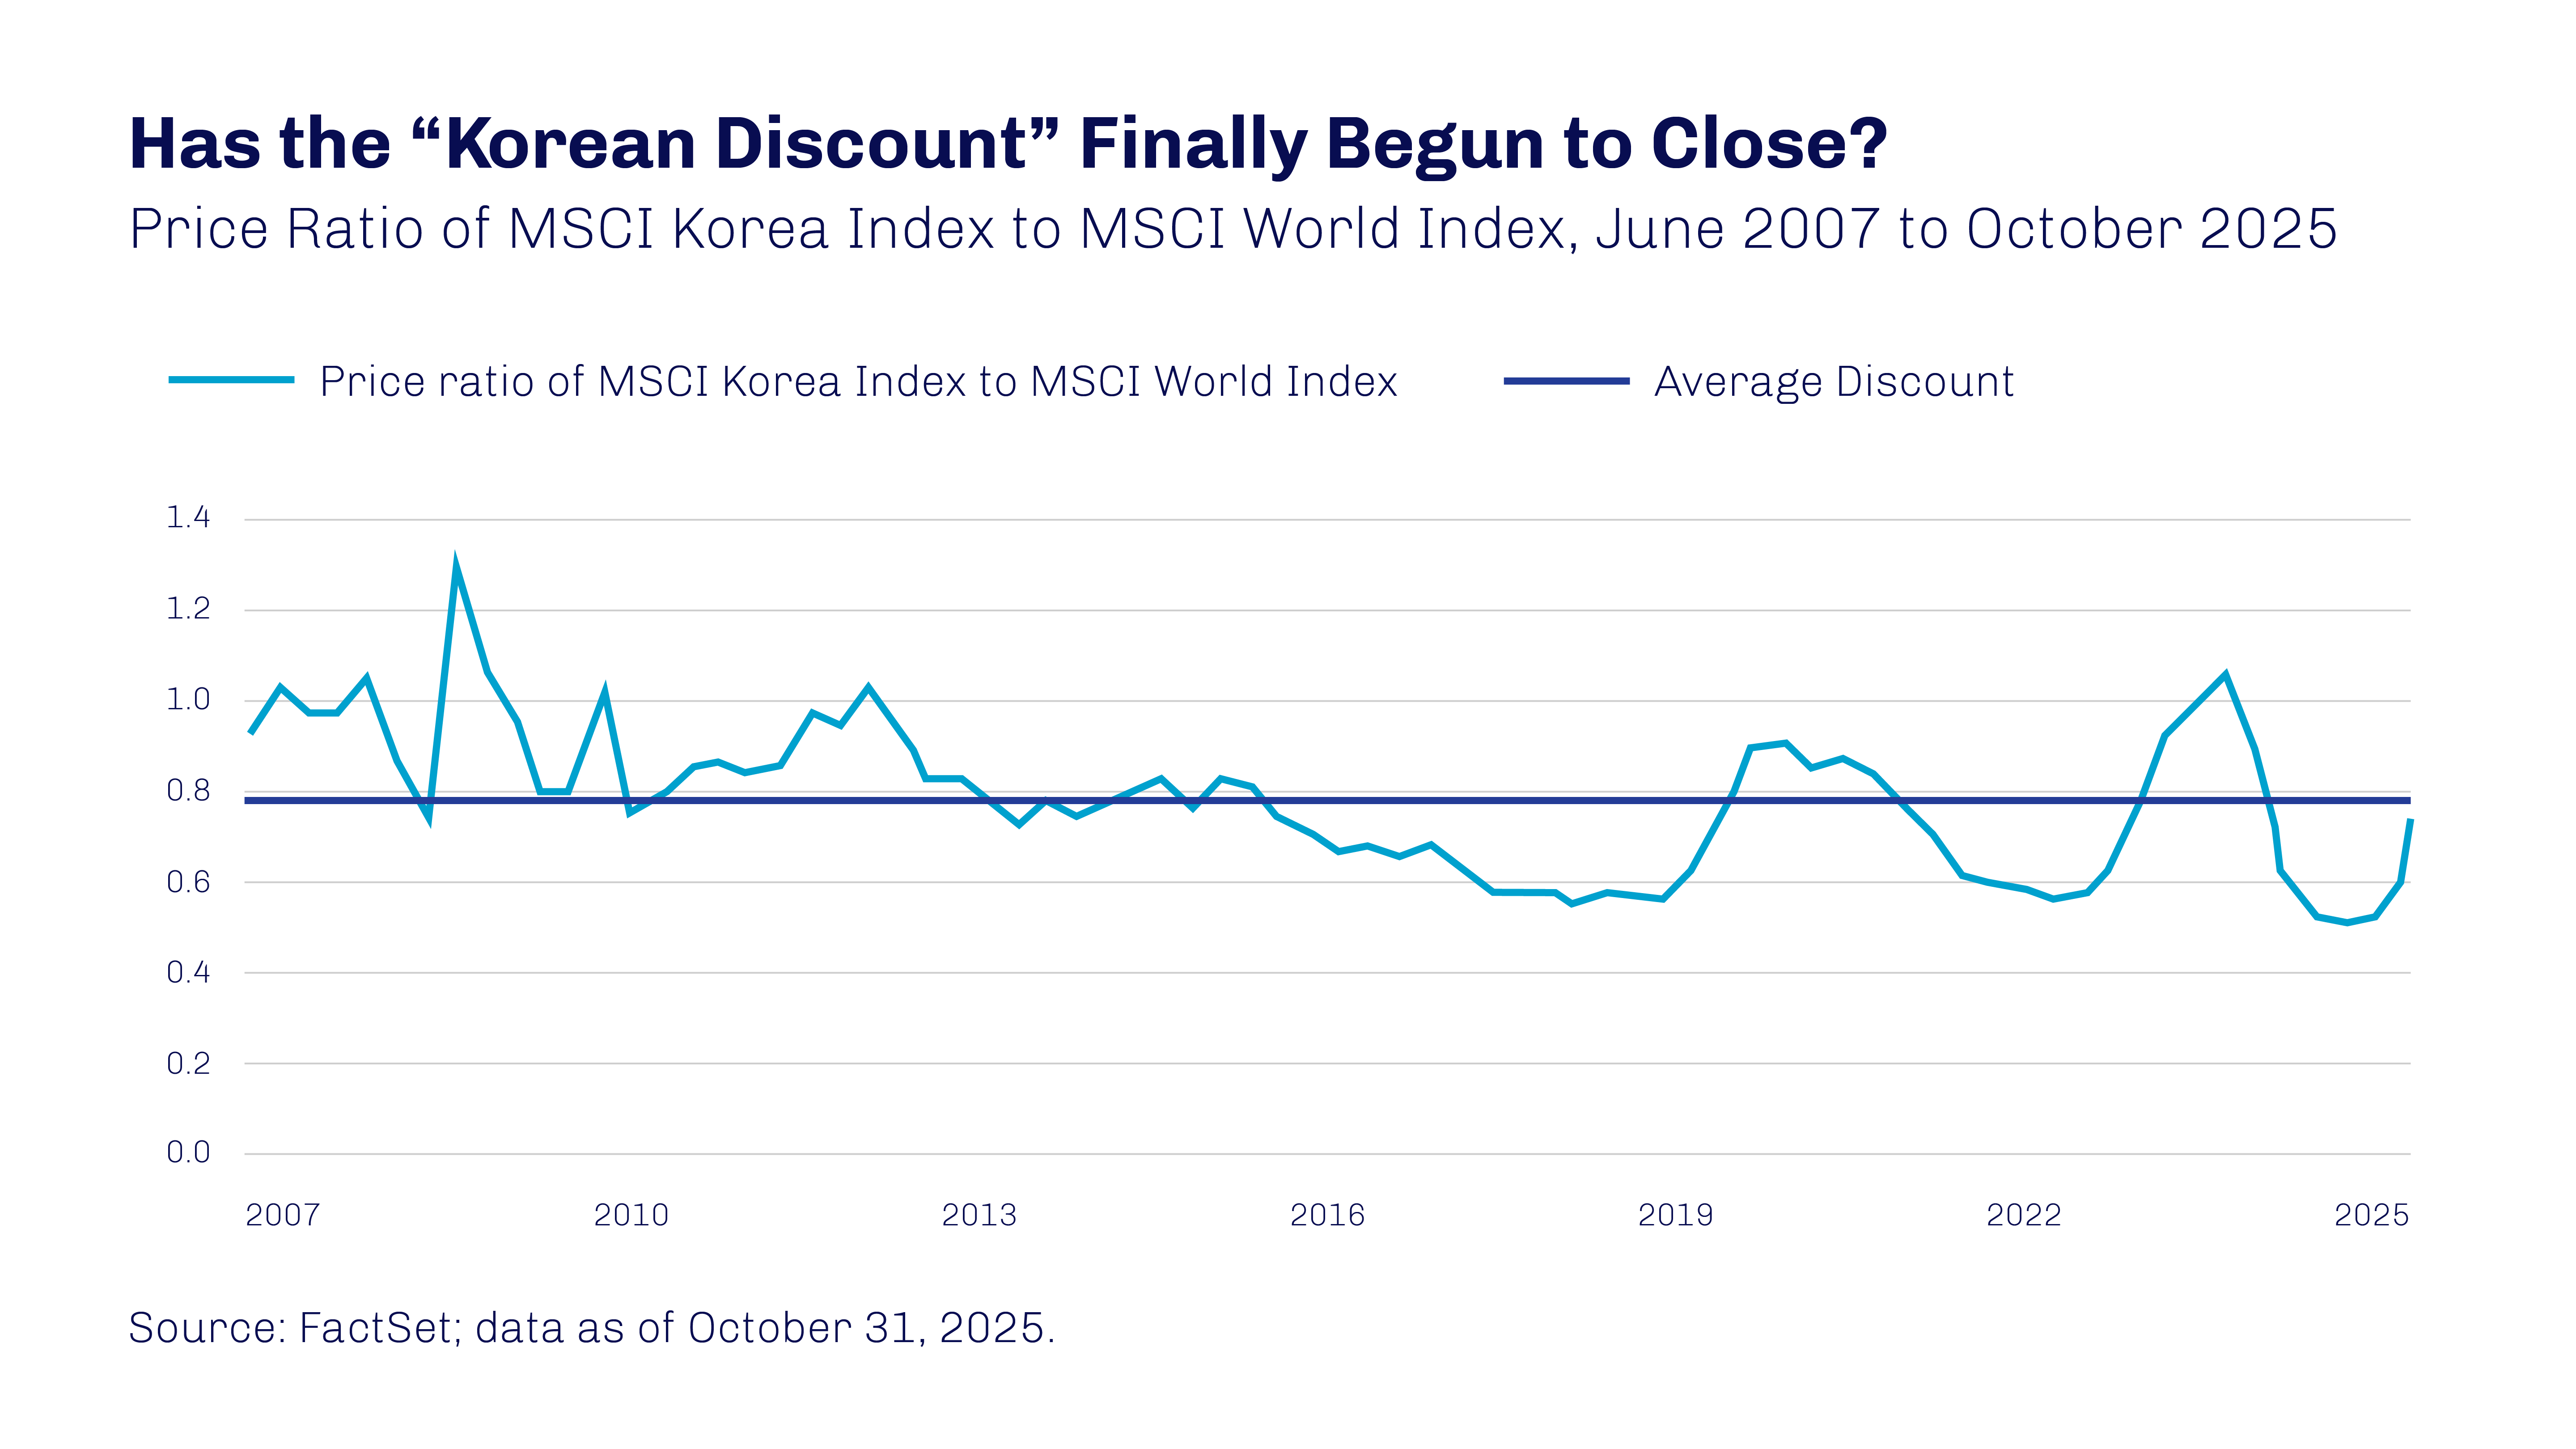
In 2024, Korea’s Financial Services Commissions introduced the Corporate Value-Up Program to combat the persistent “Korea discount” in equity valuations as a result of foreign investors’ general reluctance to invest in Korean-domiciled businesses. These reforms are focused on the expansion of fiduciary standards on corporate boards to spur changes at chaebols, the large, family-controlled conglomerates that dominate the Korean economy. While this initiative is in its early stages, we believe that it has the potential to drive a sustained interest and durable re-rating of Korean equities if it becomes a catalyst for meaningful improvements in corporate governance.
We believe reforms have the potential to drive a sustained interest and durable re-rating of Korean equities.
Fueled by a variety of other factors like growing investments in artificial intelligence and the recently announced trade deal between the US and Korea, the MSCI Korea Index has been a standout performer with an 84% gain in year-to-date 2025.1 While the “Korean discount” is still below its long-term historical average, it has begun to narrow this year. We remain cognizant of risks and challenges, and, as a result, we believe that selectivity in this market is paramount. With a track record of three decades of investing in Korea, we have observed that the country’s corporate focus on innovation in high-end precision manufacturing has contributed to a high density of world-class enterprises, including high-quality global companies with strong management teams and a qualified manufacturing base.2