


BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
Gold Is Still Shining After the Sell-Off
Portfolio Manager and Senior Research Analyst
Portfolio Manager and Senior Research Analyst
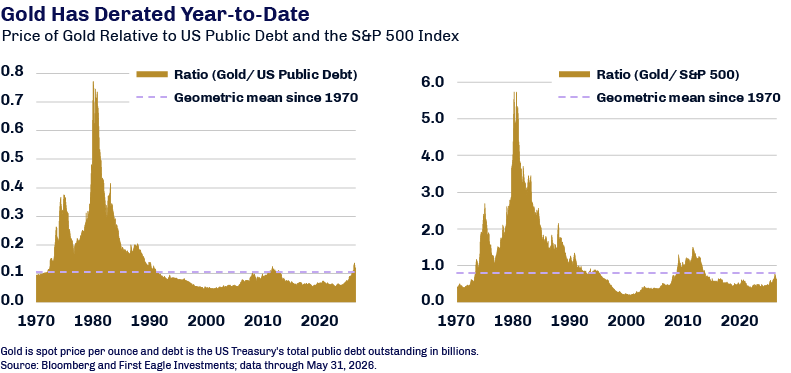
After surging to a new all-time nominal high in January, the gold price consolidated in February and sold off following the outbreak of conflict in the Middle East. Since that time, the positive inflection in job openings and the Federal Reserve’s more hawkish stance has pushed up expectations for short-term real interest rates and prompted a derating in gold, which is down nearly 8% year-to-date.1
As a result, gold has moved closer to its long-term geometric average relative to the stock of US Treasuries, down from its premium valuation in January and February. While higher interest rates may be supporting the US dollar, we also note that higher rates undermine the fiscal viability of servicing government debt as the stock of debt rolls into higher rates. In our view, the valuation of gold appears more compelling at current levels, particularly given the confluence of a generationally high stock of debt to GDP, persistent primary deficits, aging demographics in the US and growing defense spending needs.2
In comparison, gold was closer to its long-term geometric average relative to the S&P 500 Index earlier this year and is now below its historical valuation relative to equities.3 Low risk aversions in both equity and credit markets are supporting late-cycle spending and exuberance, as evidenced by the successful initial public offering of SpaceX and recent rally in semiconductor stocks.4 Should markets encounter an unexpected crisis, this may support a positive drift to the value of gold.
We continue to believe gold is best suited as a strategic allocation against adverse events, not as a tactical trade. In our view, its long-term fundamental drivers—persistent geopolitical turmoil and troubling government debt dynamics among them—currently remain intact, as does the case for strategic exposure to a potential hedge like gold.
Sourcing Excess Returns in Structured Credit
Managing Principal and Chief Investment Officer, Napier Park Global Capital
The most important question in credit today is not whether yield is still available—quite simply, we believe it is. The more important question is whether that yield is attached to risks investors can understand, control and are being adequately paid to own. In today’s market, that distinction matters.
On the surface, markets have remained resilient. Equity indexes have continued to find support from a narrow set of themes, most notably artificial intelligence-linked capital spending and higher-end consumer resilience. Credit spreads have retraced a meaningful portion of the February and March weakness, fund flows have improved, and primary markets have reopened selectively. Capital is still available, but it is becoming more conditional.
Meanwhile, investors still want yield, but they are less willing to forgive mistakes. As such, the task for managers is not simply to find more yield; it is to find yield with what we consider to be better architecture around it.
That view shaped how we entered the year. We reduced risk in areas where returns appeared asymmetric, particularly where underwriting standards had weakened or liquidity depended too heavily on continued refinancing availability. When volatility emerged in February and March, that prior de-risking mattered. It gave us the opportunity to return capital, preserve liquidity, and re-engage selectively where we believed the form of risk was clear.
For much of the last decade, investors were rewarded for adding exposure. Liquidity has been abundant, refinancing markets open and beta often doing more of the work than anyone was willing to admit. This year has been a reminder that credit is not one beta, but rather a collection of very different risks that share a label.
This year has been a reminder that credit is not one beta, but rather a collection of very different risks that share a label.
When markets are broad and forgiving, exposure can be enough. With markets as they are today, outcomes depend more on how risk is sourced, underwritten, documented, collateralized and controlled. By focusing on areas where credit meets structure, we believe complexity can potentially become a source of durable premium rather than a source of hidden risk.