Blog hero image

BLOGThe Bird's Eye View

Timely Perspectives, Unconventional Thinking 

We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.

Blog hero image

BLOGThe Bird's Eye View

Timely Perspectives, Unconventional Thinking 

We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.

Direct Lending: Where Underwriting and Structure Lead

Senior Managing Director and Chief Investment Officer of Direct Lending, Napier Park Global Capital

While credit markets rebounded in the second quarter as investor appetite for risk returned, direct lending deal volume increased slightly from the first quarter and remained well off the higher pace of second-half 2025. Add-on mergers and acquisitions financings dominated activity in the core middle market and above, while leveraged buyouts were more prevalent in the lower middle market. Lower middle market spreads widened modestly, ending the quarter at their widest level since November 2025, although spread per turn of leverage narrowed.1

Covenant-lite structures accounted for 18% of deals through the first half of 2026, up from 14% in 2025, and were primarily in the upper middle and large cap markets. In contrast, cov-lite structures represented less than 4% of deal flow in core and lower middle market loans. Lower middle market default rates over the past 12 months—2.2% by dollar amount and 2.0% by deal count—remain below 2025, with defaults concentrated in software.2 We believe these dynamics reinforce the continued appeal of the lower middle market segment where market conditions remain differentiated from the upper middle and large cap markets and where typical deal structures are highly covenanted.


We believe these dynamics reinforce the continued appeal of the lower middle market segment.

The default rate in software also highlights the importance of evaluating technology risk—including artificial intelligence (AI)—when underwriting across sectors. The types of technological change may be unique at different points in time, but we think this begins with a simple question, does AI or any other potential change in technology improve a borrower's competitive position or does it threaten it?

Software may be the clearest recent example of shared common risk factors across what on the surface appear as diversified asset classes and why we caution that traditional credit beta increasingly carries vulnerabilities that are not obvious from spread levels alone. In such an environment, we continue to focus on thoughtful processes for originating, underwriting, structuring and managing private credit.
1 Source: KBRA DLD Research; data as of June 30, 2026.
2 Source: KBRA DLD Research; data as of April 10, 2026.

The information contained in this material is provided by First Eagle Investment Management, LLC (“FEIM”) and its global subsidiaries (collectively, “First Eagle”). FEIM is an investment adviser registered with the US Securities and Exchange Commission (SEC). Registration with the SEC does not imply a certain level of skill or training.

This material is for informational purposes only and reflects prevailing conditions and the judgment of the author(s) as of the date of publication, all of which are subject to change. This material should not be relied upon as investment advice; it does not constitute a recommendation to buy or sell a security or other investment; and it is not intended to predict or depict the performance of any investment. This material is not being provided in a fiduciary capacity and is not intended to recommend any investment policy or investment strategy or consider the specific objectives or circumstances of any investor. We consider the information in this material to be accurate, but we do not represent that it is complete or should be relied upon as the sole source of appropriateness for investment.

Prospective investors should inform themselves and consult with an investment, tax or legal professional as to any applicable legal requirements, taxation and exchange control regulations in the countries of their citizenship, residence or domicile that may be relevant prior to investing.

THIS MATERIAL DOES NOT CONSTITUTE AN OFFER OR SOLICITATION IN ANY JURISDICTION WHERE OR TO ANY PERSON TO WHOM IT WOULD BE UNAUTHORIZED OR UNLAWFUL TO DO SO.

All investments involve the risk of loss of principal.

Diversification does not guarantee investment returns and does not eliminate the risk of loss.

Strategies whose investments are concentrated in a specific industry or sector may be subject to a higher degree of risk than funds whose investments are diversified and may not be suitable for all investors.

Alternative investments can be speculative and are not suitable for all investors. Investing in alternative investments is only intended for experienced and sophisticated investors who are willing and able to bear the high economic risks associated with such an investment. Investors should carefully review and consider potential risks before investing.

Certain of these risks include:

  • Loss of all or a substantial portion of the investment;
  • Lack of liquidity in that there may be no secondary market or interest in the strategy and none is expected to develop;
  • Volatility of returns;
  • Interest rate risk;
  • Restrictions on transferring interests in a private investment strategy;
  • Potential lack of diversification and resulting higher risk due to concentration within one or more sectors, industries, countries or regions;
  • Absence of information regarding valuations and pricing;
  • Complex tax structures and delays in tax reporting;
  • Less regulation and higher fees than mutual funds;
  • Use of leverage which magnifies the potential for gain or loss on amounts invested and is generally considered a speculative investment technique and increases the risks associated with investing in the strategy;
  • Carried interest, which may cause the strategy to make more speculative, higher risk investments than would be the case in absence of such arrangements; and
  • Below-investment-grade loans, which may default and adversely affect returns.

Past performance does not guarantee future results, which may vary. The value of investments and the income derived from investments will fluctuate and can go down as well as up. A loss of principal may occur.

Beta is a measure of an investment's price volatility relative to that of the overall market.

Direct lending refers to a loan agreement negotiated between a borrower and single or small group of nonbank lenders. Direct lending can also be referred to as “private credit” or “private lending.”

Private credit is an asset defined by non-bank lending where the debt is not issued or traded on the public markets. Private credit can also be referred to as “direct lending” or “private lending.”

Spread typically is used to express the difference between two interest rates.

The information presented does not reflect the performance of any fund, strategy or account managed or serviced by First Eagle, and there is no guarantee that investors will experience the type of performance reflected. There is no guarantee that any market forecast set forth in this material will be realized. There is no guarantee that any historical trend referenced herein will be repeated in the future, and there is no way to predict precisely when such a trend will begin. The mention of specific securities is not a recommendation or solicitation to buy, sell or hold any particular security and should not be relied upon as investment advice.

Availability of the products or services described may be restricted by law in certain jurisdictions. This material may not be distributed, published or used by any person or entity in any jurisdiction or country where such distribution or use would be contrary to local law or regulation.

United Kingdom

Napier Park Global Capital Ltd is authorised and regulated by the Financial Conduct Authority (FRN: 541427) in the United Kingdom.

Middle East

This material is for information purposes only and has not been, and will not be, registered with or reviewed or approved by any regulator located in the Middle East. It does not constitute or form part of any marketing initiative, any offer to issue or sell, or any solicitation of any offer to subscribe to or purchase, any products, strategies or other services, nor shall it, or the fact of its distribution, form the basis of, or be relied on in connection with, any contract resulting therefrom. In the event that the recipient of this material wishes to receive further information regarding any products, strategies or other services, it shall specifically request the same in writing from an authorized financial adviser.

Canada

Pursuant to the international adviser registration exemption in National Instrument 31-103, First Eagle Investment Management, LLC. is informing you that: (i) First Eagle Investment Management, LLC. is not registered in Canada and is advising you in reliance upon an exemption from the adviser registration under National Instrument 31-103;  (ii) First Eagle Investment Management, LLC’s jurisdiction of residence is New York, USA; (iii) there may be difficulty enforcing legal rights against First Eagle Investment Management, LLC. because it is a resident outside of Canada and all or substantially all of its assets may be situated outside of Canada.

FEF Distributors, LLC (“FEFD”) (SIPC), a limited purpose broker-dealer, distributes certain First Eagle products. FEFD does not provide services to any investor but rather provides services to its First Eagle affiliates. As such, when FEFD presents a fund, strategy or other product to a prospective investor, FEFD and its representatives do not determine whether an investment in the fund, strategy or other product is in the best interests of, or is otherwise beneficial or suitable for, the investor. No statement by FEFD should be construed as a recommendation. Investors should exercise their own judgment and/or consult with a financial professional to determine whether it is advisable for the investor to invest in any First Eagle fund, strategy or product.

First Eagle Investments is the brand name for First Eagle Investment Management, LLC and its subsidiary investment advisers.

First Eagle Alternative Credit and Napier Park are brand names for the two subsidiary investment advisers engaged in the alternative credit business.

© 2026 First Eagle Investment Management, LLC. All rights reserved.

    Can Buybacks Keep Yields in Check?

    Idanna Appio Headshot

    Portfolio Manager and Senior Research Analyst

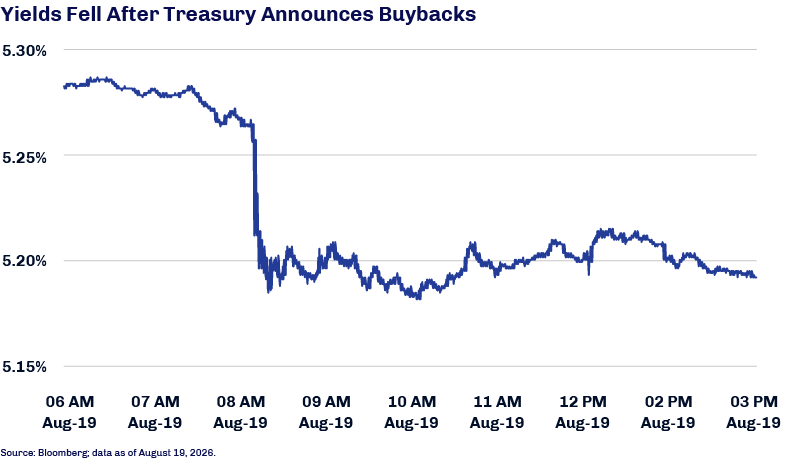
    US Treasury Secretary Scott Bessent announced plans to at least double buyback support for longer-dated government bonds with the goal of reducing longer-term yields. This buyback announcement had an immediate and measurable impact on yields—the 30-year Treasury yield fell by as much as 10 basis points after recently reaching its highest level since 2007.1 But we are skeptical of the sustainability of the relief.

    We estimate that the implied size of these buybacks would total $28 billion, which is relatively small compared to the $4 trillion balance of outstanding bonds at these tenors.2 Additionally, to the extent that this buyback does ease longer term rates, it does so at a time when financial conditions are already quite easy and inflation pressures persist.

    Perhaps more troubling, the Treasury will need to issue more shorter-dated debt to fund these buybacks, implying more interest-rate risk for the Treasury down the road when maturing obligations must be refinanced at higher prevailing rates. This rollover risk is particularly problematic in light of today’s fiscal situation with a large primary deficit and high federal debt.

    While government intervention in other sovereign bond markets—typically in emerging economies—have sometimes been effective during periods of stress and dislocation, a small intervention by US Treasury seems inadequate to offset the slow grind-up in Treasury yields due to higher expected short rates and higher term premiums on longer bonds. Moreover, we think efforts to contain the cost of debt through financial repression rather than adopting fiscal discipline to reduce deficits will eventually take its toll and be felt in other markets, as gold strengthened and US dollar weakened in tandem with this announcement.3
    buybacks-keep-yields

    1 Source: Bloomberg; data as of August 19, 2026.
    2 Source: US Treasury; data as of March 31, 2026.
    3 Source: Bloomberg; data as of August 19, 2026.
     

    The information contained in this material is provided by First Eagle Investment Management, LLC (“FEIM”) and its global subsidiaries (collectively, “First Eagle”). FEIM is an investment adviser registered with the US Securities and Exchange Commission (SEC). Registration with the SEC does not imply a certain level of skill or training.

    This material is for informational purposes only and reflects prevailing conditions and the judgment of the author(s) as of the date of publication, all of which are subject to change. This material should not be relied upon as investment advice; it does not constitute a recommendation to buy or sell a security or other investment; and it is not intended to predict or depict the performance of any investment. This material is not being provided in a fiduciary capacity and is not intended to recommend any investment policy or investment strategy or consider the specific objectives or circumstances of any investor. We consider the information in this material to be accurate, but we do not represent that it is complete or should be relied upon as the sole source of appropriateness for investment.

    Prospective investors should inform themselves and consult with an investment, tax or legal professional as to any applicable legal requirements, taxation and exchange control regulations in the countries of their citizenship, residence or domicile that may be relevant prior to investing.

    THIS MATERIAL DOES NOT CONSTITUTE AN OFFER OR SOLICITATION IN ANY JURISDICTION WHERE OR TO ANY PERSON TO WHOM IT WOULD BE UNAUTHORIZED OR UNLAWFUL TO DO SO.

    All investments involve the risk of loss of principal.

    Past performance does not guarantee future results, which may vary. The value of investments and the income derived from investments will fluctuate and can go down as well as up. A loss of principal may occur.

    Investment in gold and gold-related investments present certain risks, including political and economic risks affecting the price of gold and other precious metals like changes in US or foreign tax, currency or mining laws, increased environmental costs, international monetary and political policies, economic conditions within an individual country, trade imbalances and trade or currency restrictions between countries. The price of gold, in turn, is likely to affect the market prices of securities of companies mining or processing gold and, accordingly, the value of investments in such securities may also be affected. Gold-related investments as a group have not performed as well as the stock market in general during periods when the US dollar is strong, inflation is low and general economic conditions are stable. In addition, returns on gold-related investments have traditionally been more volatile than investments in broader equity or debt markets. Investment in gold and gold-related investments may be speculative and may be subject to greater price volatility than investments in other assets and types of companies.

    30-year Treasury yield is the interest rate paid on a US Treasury bond with a maturity of 30 years upon issuance.

    Term premium is the extra compensation investors require for bearing risk that interest rates may change over the life of a bond.

    The information presented does not reflect the performance of any fund, strategy or account managed or serviced by First Eagle, and there is no guarantee that investors will experience the type of performance reflected. There is no guarantee that any market forecast set forth in this material will be realized. There is no guarantee that any historical trend referenced herein will be repeated in the future, and there is no way to predict precisely when such a trend will begin. The mention of specific securities is not a recommendation or solicitation to buy, sell or hold any particular security and should not be relied upon as investment advice.

    Availability of the products or services described may be restricted by law in certain jurisdictions. This material may not be distributed, published or used by any person or entity in any jurisdiction or country where such distribution or use would be contrary to local law or regulation.

    United Kingdom

    Napier Park Global Capital Ltd is authorised and regulated by the Financial Conduct Authority (FRN: 541427) in the United Kingdom.

    Middle East

    This material is for information purposes only and has not been, and will not be, registered with or reviewed or approved by any regulator located in the Middle East. It does not constitute or form part of any marketing initiative, any offer to issue or sell, or any solicitation of any offer to subscribe to or purchase, any products, strategies or other services, nor shall it, or the fact of its distribution, form the basis of, or be relied on in connection with, any contract resulting therefrom. In the event that the recipient of this material wishes to receive further information regarding any products, strategies or other services, it shall specifically request the same in writing from an authorized financial adviser.

    Canada

    Pursuant to the international adviser registration exemption in National Instrument 31-103, First Eagle Investment Management, LLC. is informing you that: (i) First Eagle Investment Management, LLC. is not registered in Canada and is advising you in reliance upon an exemption from the adviser registration under National Instrument 31-103; (ii) First Eagle Investment Management, LLC’s jurisdiction of residence is New York, USA; (iii) there may be difficulty enforcing legal rights against First Eagle Investment Management, LLC. because it is a resident outside of Canada and all or substantially all of its assets may be situated outside of Canada.

    FEF Distributors, LLC (“FEFD”) (SIPC), a limited purpose broker-dealer, distributes certain First Eagle products. FEFD does not provide services to any investor but rather provides services to its First Eagle affiliates. As such, when FEFD presents a fund, strategy or other product to a prospective investor, FEFD and its representatives do not determine whether an investment in the fund, strategy or other product is in the best interests of, or is otherwise beneficial or suitable for, the investor. No statement by FEFD should be construed as a recommendation. Investors should exercise their own judgment and/or consult with a financial professional to determine whether it is advisable for the investor to invest in any First Eagle fund, strategy or product.

    First Eagle Investments is the brand name for First Eagle Investment Management, LLC and its subsidiary investment advisers.

    © 2026 First Eagle Investment Management, LLC. All rights reserved.