


BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
Yen Intervention: Watching Our Own Back
Portfolio Manager and Senior Research Analyst
Japan intervened in foreign exchange markets in late July, selling approximately $85 billion of reserves to support the yen, which had fallen to its weakest level against the dollar since the 1985 Plaza Accord. Unusually, the US intervened alongside Japanese authorities.
With its massive store of dollar-denominated reserves in both deposits and securities, Japan’s Ministry of Finance does not need to sell Treasuries to fund yen purchases. Still, the risk of large-scale Treasury sales was one the US likely wanted to avoid. Such sales could push Treasury yields higher—an unwelcome prospect given the volume of US government debt that is continually rolled over at prevailing rates.
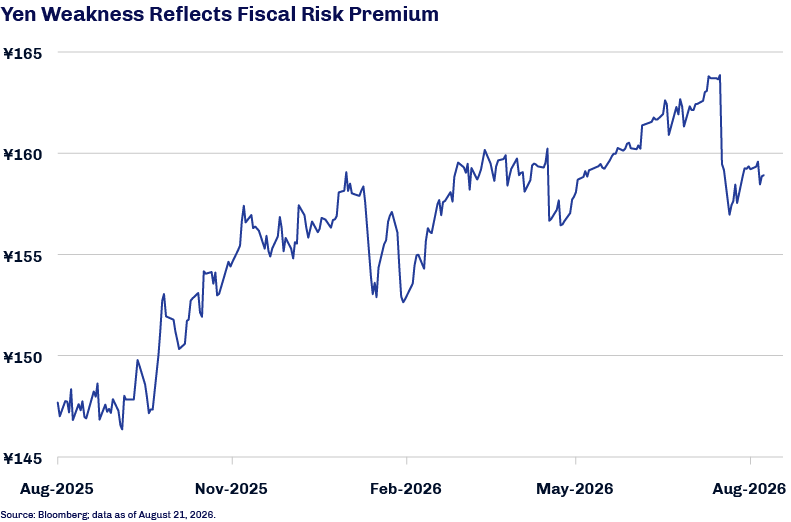
Joint intervention should improve the odds of strengthening the yen in the near term by adding buying power and signaling that both governments favor a stronger currency. Indeed, the intervention strengthened the yen from 163.7 to 155.5, though it has subsequently pulled back to around 158.9.1 But intervention is no substitute for addressing the underlying monetary and fiscal policy mix.
The yen is exceptionally weak relative to both history and interest-rate differentials, whether nominal or real. In our view, faster Bank of Japan rate hikes alone are unlikely to solve the problem. Instead, the yen and Japanese government bonds increasingly appear to reflect a fiscal risk premium: the currency has weakened even as Japanese interest rates have risen.
Yet, Japan’s fiscal position may be less precarious than headline debt levels suggest. Japan has a roughly five-year window in which the relationship between growth and interest rates remains favorable, while its primary deficit has improved more since the Covid era than those of many other major economies. Credible fiscal consolidation during this window could reduce the risk premium, support the yen and lessen the burden on monetary policy.
Direct Lending: Where Underwriting and Structure Lead

Senior Managing Director and Chief Investment Officer of Direct Lending, Napier Park Global Capital
While credit markets rebounded in the second quarter as investor appetite for risk returned, direct lending deal volume increased slightly from the first quarter and remained well off the higher pace of second-half 2025. Add-on mergers and acquisitions financings dominated activity in the core middle market and above, while leveraged buyouts were more prevalent in the lower middle market. Lower middle market spreads widened modestly, ending the quarter at their widest level since November 2025, although spread per turn of leverage narrowed.1
Covenant-lite structures accounted for 18% of deals through the first half of 2026, up from 14% in 2025, and were primarily in the upper middle and large cap markets. In contrast, cov-lite structures represented less than 4% of deal flow in core and lower middle market loans. Lower middle market default rates over the past 12 months—2.2% by dollar amount and 2.0% by deal count—remain below 2025, with defaults concentrated in software.2 We believe these dynamics reinforce the continued appeal of the lower middle market segment where market conditions remain differentiated from the upper middle and large cap markets and where typical deal structures are highly covenanted.
We believe these dynamics reinforce the continued appeal of the lower middle market segment.
The default rate in software also highlights the importance of evaluating technology risk—including artificial intelligence (AI)—when underwriting across sectors. The types of technological change may be unique at different points in time, but we think this begins with a simple question, does AI or any other potential change in technology improve a borrower's competitive position or does it threaten it?
Software may be the clearest recent example of shared common risk factors across what on the surface appear as diversified asset classes and why we caution that traditional credit beta increasingly carries vulnerabilities that are not obvious from spread levels alone. In such an environment, we continue to focus on thoughtful processes for originating, underwriting, structuring and managing private credit.