BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
BLOGThe Bird's Eye View
Timely Perspectives, Unconventional Thinking
We’re excited to share timely market insights, thoughtful perspectives and expert commentary as part of our commitment to providing modern investment solutions to modern challenges.
The Shift from Efficiency to Resilience
Portfolio Manager and Senior Research Analyst
Portfolio Manager and Senior Research Analyst
For decades, Western economies maximized efficiency by pushing production to the lowest-cost locations, minimizing inventories and relying on global markets for energy, critical minerals, key intermediate components and manufactured goods. This model lifted returns as capital-light businesses became the clear winners in public equity markets. At the same time, those economies became overly reliant on distant, fragile, or potentially adversarial sources for critical inputs, exposing them to supply risks and potential trade restrictions.
The pandemic, Russia’s war in Ukraine, economic and strategic rivalry with China and disruptions in the Middle East have exposed the vulnerabilities of this system and prompted the need for strategic autonomy and self-reliance. Rebuilding resilience may entail increasing investment in defense production, semiconductors, critical minerals, battery manufacturing, energy generation, electrical grids, transportation networks and domestic industrial capacity. Artificial intelligence (AI) spending has accelerated this transition by driving demand for power, land, steel, cooling systems, chips, transformers and transmission capacity.
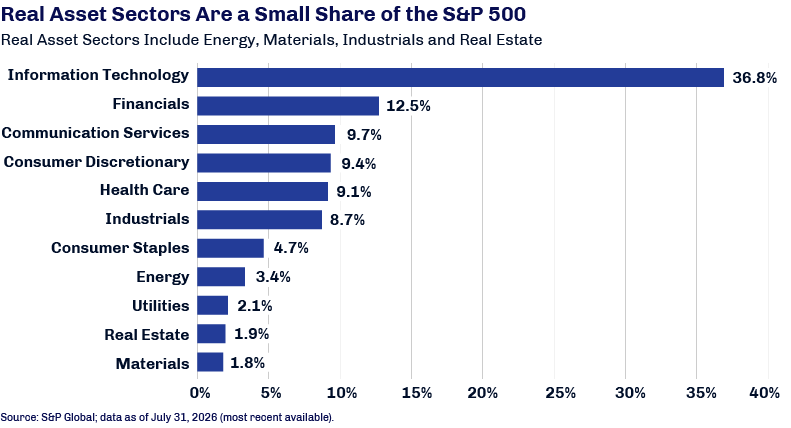
Despite this massive need for investment, market-cap weighted benchmarks still reflect the capital-light era. Information technology and communication services together represented roughly 46% of the S&P 500 Index, while energy, materials, industrials and real estate are approximately 14% of the index, near historical lows. Excluding industrials, real assets represent just 6% of the Index, less than the weight of Nvidia alone.1
Even as resilience becomes a strategic priority and capital flows are directed toward expanding physical capacity, not all real assets are automatically good investments. We take a selective approach, focusing on businesses with cost-competitive assets in areas where demand is strong and capacity is scarce, and which have potential for advantaged reinvestment opportunities or rational management teams that could return excess cash to shareholders.
Can Asset-Based Lending Provide Spreads with Benefits?

Senior Managing Director and Head of Asset-Based Loans

Managing Director
With credit spreads near historical tights, risk appetites have been supported by elevated yields and resilient economic growth.1 Although capital is still available, it has become more conditional as investors are less willing to forgive mistakes. In such an environment, we like the differentiated opportunity set within asset-based lending (ABL).
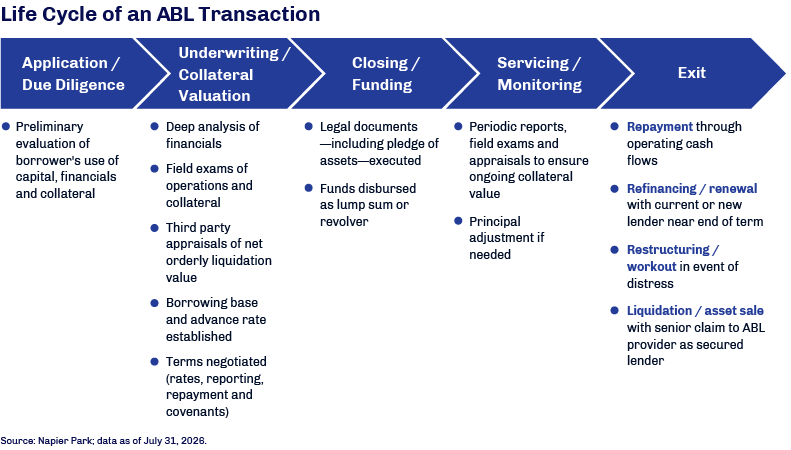
ABL facilities are corporate loans supported by specific assets of the borrower, such as inventory, accounts receivable, real estate, machinery and equipment, and intellectual property. These facilities carry floating rates, typically have tenors of five years or less, and can be structured as term loans or revolving lines of credit. Done right, ABL facilities potentially offer attractive yields and appealing downside mitigation through strong structural provisions and explicit collateral backing.
In our view, the value of an ABL strategy is dependent on how collateral is sourced, underwritten, monitored, and controlled. Relationship-driven sourcing—which is often built on credibility with sponsors, companies, banks and other lenders—can provide established managers with differentiated access to investment opportunities and act as a barrier to entry. Collateral is evaluated as a first line of defense under real downside scenarios. Asset valuations must be dynamically verified and monitored throughout the loan term—not only under base-case assumptions, but also under various liquidation scenarios.
Beyond the evaluation and monitoring of collateral, structuring covenants, reporting practices, cash controls, collateral triggers, remedies and intercreditor arrangements can provide risk mitigation should conditions soften or deteriorate. Lastly, we believe ABL requires sound business judgment—understanding management quality, liquidity, customer concentration, supplier dynamics and the durability of the borrower’s model.
Within an increasingly competitive and commodified credit market, ABL is one of our highest-conviction areas because we believe ABL can offer “spreads with benefits” when the collateral is paired with architecture that provides visibility, verification, priority and enforceability.